Credit Impulse and Semi CapEx: The 6-Month Lead
2026-10-22

The relationship between the 10-year U.S. Treasury yield and semiconductor valuations has become one of the most closely watched macro-financial linkages in the technology market. Semiconductor companies are often valued on expectations of future earnings, long-term growth, technological leadership, and expanding demand from areas such as artificial intelligence, cloud computing, advanced networking, and automotive electronics. At the same time, those future cash flows are discounted against a market interest-rate environment that can change rapidly.
When the 10-year Treasury yield rises, the theoretical present value of future earnings falls, particularly for companies whose expected growth lies far into the future. Yet semiconductor valuations do not respond mechanically to every change in Treasury yields. Sometimes yields rise while semiconductor stocks remain resilient because earnings expectations are improving even faster. In other periods, a relatively small increase in yields can trigger a sharp valuation adjustment.
This apparent contradiction points toward the idea of a critical threshold. Rather than assuming that one specific yield level permanently determines semiconductor valuations, it is more useful to think about zones where the interaction between discount rates, earnings growth, liquidity, and risk appetite changes character.
The 10-year Treasury yield is more than a benchmark for government borrowing costs. It serves as a reference point for the pricing of a wide range of financial assets, including corporate bonds, equities, mortgages, and long-duration growth companies. When the yield changes, investors reassess the return they require for taking risk elsewhere.
For semiconductor companies, this matters because a significant portion of their valuation can depend on profits expected several years into the future. A company investing heavily today in advanced manufacturing, AI accelerators, memory technology, or next-generation packaging may not realize the full economic value of those investments immediately.
The farther into the future the expected cash flow, the greater its sensitivity to changes in the discount rate. This is why high-growth semiconductor stocks can sometimes react more strongly to Treasury yields than mature companies with stable near-term cash generation.
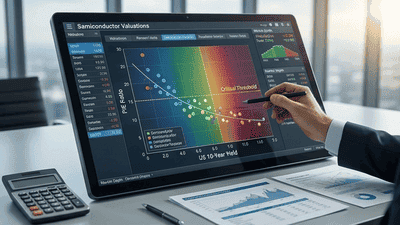
The most direct mechanism is the discount-rate channel. Equity valuation models convert expected future cash flows into a present value. When the risk-free rate rises, the discount rate generally rises as well, reducing the present value of distant earnings if other assumptions remain unchanged.
In practice, investors do not constantly rebuild detailed valuation models for every semiconductor company. Instead, the effect often appears through changes in valuation multiples. Price-to-earnings ratios, price-to-sales ratios, enterprise-value-to-EBITDA multiples, and other market measures can contract when investors demand a higher return for holding equities.
This process is particularly visible in periods when Treasury yields rise rapidly. The market may not need to believe that semiconductor earnings are falling. It may simply decide that the same earnings stream should command a lower multiple because the alternative return available in government bonds has become more attractive.
Semiconductor companies combine several characteristics that can increase their sensitivity to macroeconomic conditions. They often operate in cyclical industries, require significant capital expenditure, and depend on rapidly changing technology demand. At the same time, leading semiconductor companies can generate exceptional growth when a new product cycle emerges.
This combination creates a valuation structure in which expectations matter enormously. When investors believe that AI infrastructure, high-performance computing, advanced memory, or networking demand will expand rapidly, they may accept high valuation multiples. If interest rates rise while those expectations remain intact, the valuation pressure may be manageable.
But if higher yields begin to challenge the assumptions behind long-term growth, the adjustment can become much sharper. The market can simultaneously raise the discount rate and lower its growth expectations, producing a much larger valuation effect than the Treasury move alone would suggest.
Financial markets often search for a specific Treasury yield level that supposedly determines whether technology valuations can remain elevated. Such precision can be misleading. The critical threshold changes with inflation expectations, economic growth, earnings momentum, liquidity, and the level of starting valuations.
A 10-year yield that appears restrictive in one environment may be relatively manageable in another. If semiconductor earnings are accelerating rapidly and corporate balance sheets are strong, investors may tolerate higher yields. If earnings growth is slowing and valuations are already stretched, the same yield can become much more consequential.
It is therefore more useful to think in terms of a pressure zone. As yields rise, the market gradually demands stronger earnings justification for high semiconductor multiples. Beyond a certain point, the required growth rate may become difficult to reconcile with prevailing valuations.
The nominal 10-year Treasury yield is only part of the equation. Real yields provide another important lens because they attempt to separate the interest rate from expected inflation.
When real yields rise, the opportunity cost of holding long-duration assets increases without an equivalent inflation component supporting nominal revenue growth. Growth-oriented technology companies can therefore face greater valuation pressure from rising real yields than from a comparable move in nominal yields driven primarily by higher inflation expectations.
This distinction is especially relevant for semiconductor companies because their future growth assumptions often extend over many years. A persistent rise in real yields can force investors to reconsider how much they are willing to pay for earnings that may not materialize until the later stages of a technology cycle.
There are important periods when semiconductor valuations rise despite higher Treasury yields. The reason is simple: earnings expectations can change faster than discount rates.
Suppose a semiconductor company is expected to experience a substantial increase in revenue because demand for advanced computing infrastructure is accelerating. If the market raises its earnings forecasts significantly, that improvement can offset some of the valuation pressure created by higher interest rates.
This helps explain why the yield-equity relationship is not consistently negative. A rising 10-year yield caused by stronger economic growth can coexist with rising semiconductor earnings expectations. In such a scenario, the market may interpret higher yields as evidence of stronger nominal growth rather than simply as a threat to valuation multiples.
The problem emerges when yields continue climbing after growth expectations have stopped improving. At that point, the balance can shift from an earnings-driven market toward a multiple-compression market.
The rate of change can be as important as the absolute yield level. A gradual increase in Treasury yields gives companies and investors more time to adapt. A rapid move can force portfolios to adjust before earnings expectations have time to catch up.
For semiconductor stocks, sudden yield increases can trigger multiple forms of selling at once. Quantitative funds may reduce exposure to high-duration equities, discretionary investors may rebalance toward bonds, and growth-oriented investors may lower their valuation assumptions.
This creates a feedback effect. Falling semiconductor stocks can weaken investor confidence, which can increase volatility and encourage additional risk reduction. If the move in yields is accompanied by wider credit spreads, the financial tightening becomes even more visible.
The Treasury yield should therefore be examined alongside corporate credit spreads. A rising risk-free rate does not necessarily indicate financial stress. But when Treasury yields rise together with widening corporate spreads, the market is receiving a different signal.
Higher government yields increase the baseline cost of capital, while wider credit spreads increase the compensation investors demand for taking corporate credit risk. Semiconductor companies may then face higher financing costs, while customers may become more cautious about inventory and capital expenditure.
This combination can have a much stronger impact than a Treasury move by itself. The semiconductor valuation framework is no longer dealing solely with a higher discount rate; it is also dealing with a potentially weaker investment environment.
Interest rates also influence currency markets, creating another connection between Treasury yields and semiconductor valuations. Higher U.S. yields can support the dollar by making dollar-denominated assets more attractive. A stronger dollar can then affect Asian semiconductor manufacturers through revenue translation, imported equipment costs, and global purchasing power.
For exporters, currency depreciation against the dollar can increase the local-currency value of dollar revenue. At the same time, imported semiconductor equipment and certain materials may become more expensive. The result depends on the company's revenue mix, cost structure, hedging strategy, and geographic exposure.
This is another reason the Treasury yield should not be interpreted in isolation. The yield affects financial conditions, financial conditions influence exchange rates, and exchange rates feed back into semiconductor earnings and capital expenditure.
Semiconductor valuations are closely connected to expectations for future capital expenditure. Fabrication plants, advanced packaging facilities, memory capacity, testing infrastructure, and specialized equipment require substantial investment. Higher financing costs can influence the timing and economics of those projects.
Yet capital expenditure is not purely interest-rate driven. Technology competition can be powerful enough to override short-term financial constraints. Companies may continue investing aggressively in advanced nodes or AI infrastructure because delaying investment could mean losing strategic market share.
This creates a fascinating tension. Higher yields can reduce the valuation investors are willing to assign to semiconductor companies, while the same companies may continue spending heavily because their long-term strategic objectives have not changed.
When that happens, the market can temporarily separate valuation from physical investment. Eventually, however, earnings growth must justify the capital deployed. If it does not, the valuation pressure can become more persistent.
The emergence of AI infrastructure has complicated the historical relationship between interest rates and semiconductor valuations. Demand for GPUs, custom accelerators, high-bandwidth memory, networking chips, advanced packaging, and data-center infrastructure has created a new investment cycle with unusually strong strategic momentum.
In previous semiconductor cycles, rising yields could more easily coincide with declining technology investment expectations. Today, some segments are supported by structural spending programs that may continue despite changes in financial conditions.
That does not eliminate rate sensitivity. Instead, it changes where the sensitivity appears. A company with extraordinary AI-driven earnings growth may tolerate a higher discount rate, while a semiconductor company dependent on a weaker consumer-electronics cycle may experience much stronger valuation pressure under the same yield environment.
As Treasury yields rise, the market tends to become increasingly selective. Investors begin separating companies with visible earnings growth from those whose valuations depend primarily on distant expectations. Semiconductor companies with strong free cash flow, durable customer relationships, and clear demand visibility may be treated differently from companies whose investment case requires several favorable assumptions to remain intact.
This is where the idea of a critical threshold becomes useful. It does not mean that every semiconductor stock falls once the 10-year yield reaches a particular level. Instead, it suggests that the tolerance for valuation uncertainty decreases as the risk-free rate rises.
At lower yields, investors may be willing to pay for optionality. At higher yields, they may demand evidence. The market gradually shifts from “show me the future” toward “show me the earnings.”
A useful macro framework begins with the direction of the 10-year Treasury yield. The next question is why the yield is moving. If yields are rising because growth expectations are improving, semiconductor earnings may remain resilient. If yields are rising because inflation expectations are becoming difficult to control, valuation pressure may become more significant.
The next layer is real yields. Rising real yields generally deserve closer attention from investors focused on long-duration technology valuations. After that comes the credit market. Stable credit spreads suggest that the financial system is absorbing higher rates, while widening spreads can indicate a more restrictive environment.
Finally, the yield signal should be compared with semiconductor fundamentals: memory pricing, foundry utilization, inventory levels, equipment orders, AI accelerator demand, capital expenditure plans, and earnings revisions. The strongest valuation pressure tends to emerge when higher yields coincide with deteriorating semiconductor fundamentals rather than when either factor moves alone.
The 10-year Treasury yield sits at the center of a much wider financial network. It affects discount rates, bond-market competition, credit conditions, exchange rates, and investor risk appetite. Those variables then influence semiconductor demand, production costs, capital expenditure, and valuation.
That is why a single yield chart rarely tells the complete story. A semiconductor market supported by strong earnings growth, healthy credit markets, stable currencies, and resilient demand can absorb higher Treasury yields more easily than a market already facing inventory problems and slowing orders.
The critical threshold is therefore dynamic. It moves with the strength of the semiconductor cycle and the credibility of future earnings growth. The higher the expected growth and the stronger the balance sheet, the greater the market's ability to tolerate higher rates. Conversely, when growth expectations weaken, even a modest change in the discount rate can become meaningful.
The relationship between the 10-year Treasury yield and semiconductor valuations is best understood as a contest between discount rates and earnings expectations. Rising yields create valuation pressure by increasing the opportunity cost of equities and reducing the present value of distant cash flows. But strong semiconductor earnings growth, technological breakthroughs, and strategic investment can offset that pressure.
The most important threshold is therefore not a fixed number. It is the point at which the market begins to believe that expected semiconductor earnings growth is no longer sufficient to justify the valuation premium created by a higher cost of capital.
Watching that transition requires more than monitoring the Treasury market. Real yields, credit spreads, exchange rates, commodity costs, capital expenditure, inventory, and semiconductor pricing all contribute to the final outcome. When these forces reinforce one another, the valuation response can be powerful. When they diverge, the headline relationship becomes much less straightforward.
For semiconductor investors and analysts, the central lesson is simple but useful: the 10-year Treasury yield matters not because it automatically dictates where semiconductor stocks should trade, but because it changes the financial hurdle that future growth must overcome. The critical threshold is reached when that hurdle becomes large enough to force the market to reconsider how much it is willing to pay for tomorrow's semiconductor earnings.